
Best In Class Pricing
A pricing structure built to lower transaction costs, whether you are a small community bank or a regulated FI with millions of members.
Peer-To-Peer
Members send money to a phone number or email. The recipient taps a link and chooses a bank account, debit card or digital wallet. They do not need the same app or a new download.
In ShortNeural Payments P2P is a white-labeled peer-to-peer payment experience that runs natively inside a financial institution’s existing mobile banking app. Senders send money to anyone by phone number or email. Recipients do not need to bank with the sender’s institution or download an app; they choose to receive funds to a bank account, debit card or digital wallet. Members can also schedule one-time or recurring payments, such as monthly rent, and use Request For Pay to ask anyone for money by phone number or email; people outside the institution pay from a debit card on the institution’s branded page. Every transfer is screened by the Neural Payments Fraud Rules Engine. Most institutions can launch in as little as 90 days.
What You Get
A pricing structure built to lower transaction costs, whether you are a small community bank or a regulated FI with millions of members.
Real-time fraud detection screens every transfer. Rules are changed in house, so your team can respond to new patterns the same day.
Launch a customized P2P experience in as little as 90 days with pre-built integrations to leading digital banking providers.
Keep money movement inside your brand instead of a third-party app. Every outside recipient is a potential new member.
Fully white-labeled. The send flow, the text message and the claim page all carry your institution’s name, not ours.
Recipients choose a bank account, debit card or digital wallet. They never have to sign up for anything to get their money.
How It Feels
Real screens, in the order a member and their recipient see them.
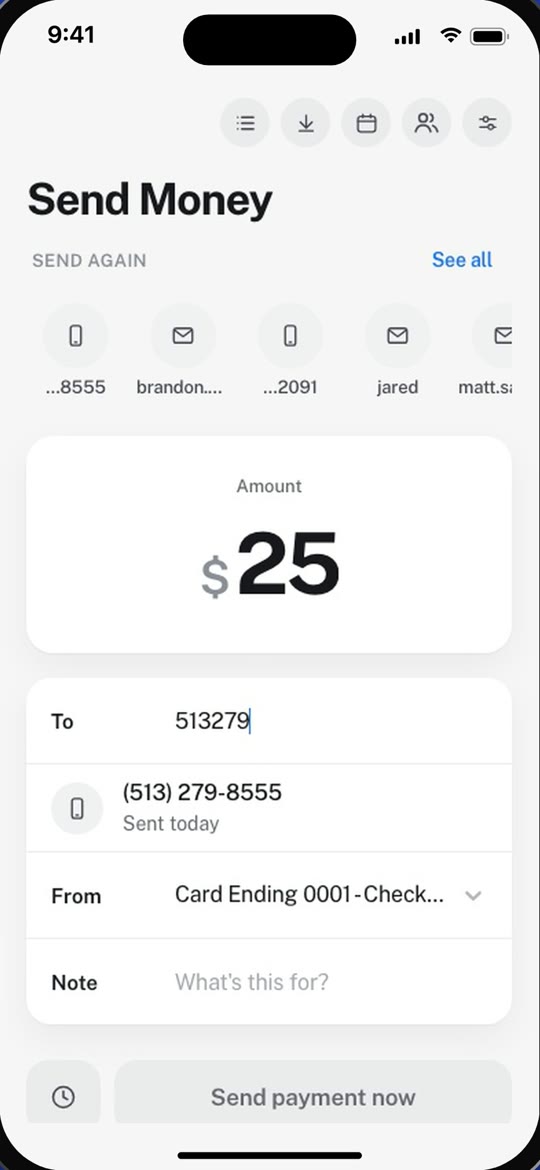
Sender
The member opens Send Money in their own banking app and enters $25.
Sender
No handle, no username, no asking which app they use. A phone number or email is enough.
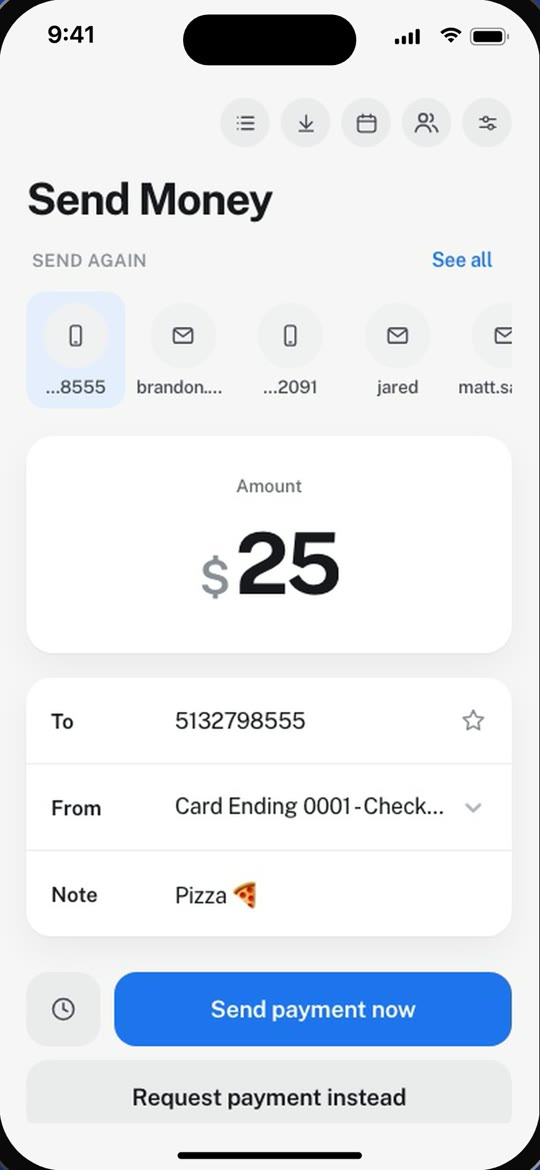
Sender
One tap opens Messages with the claim link already written. The member just hits send.
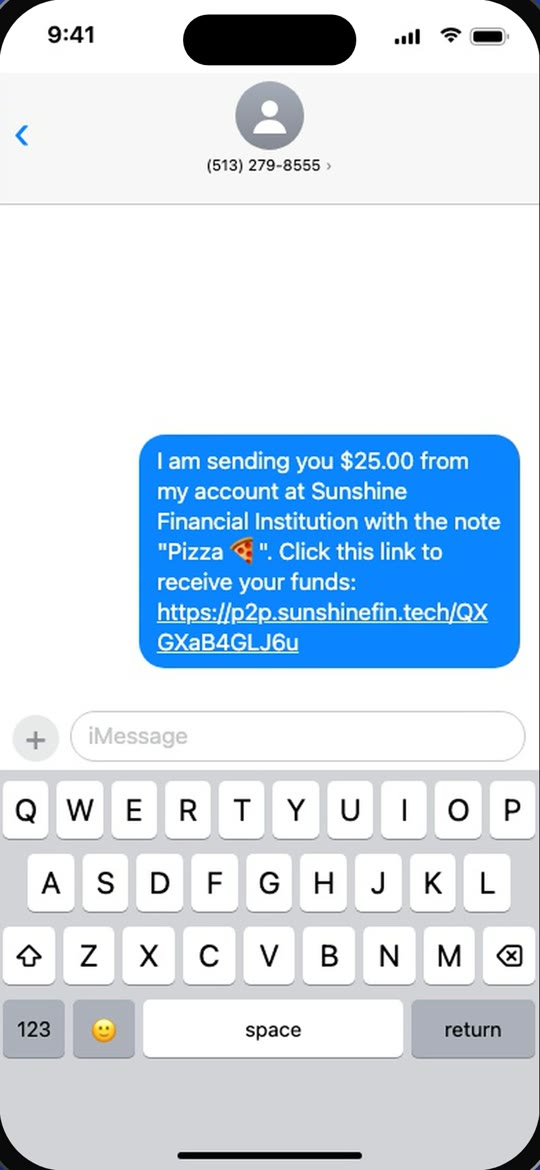
Recipient
The message comes from someone they know, in a thread they already trust.
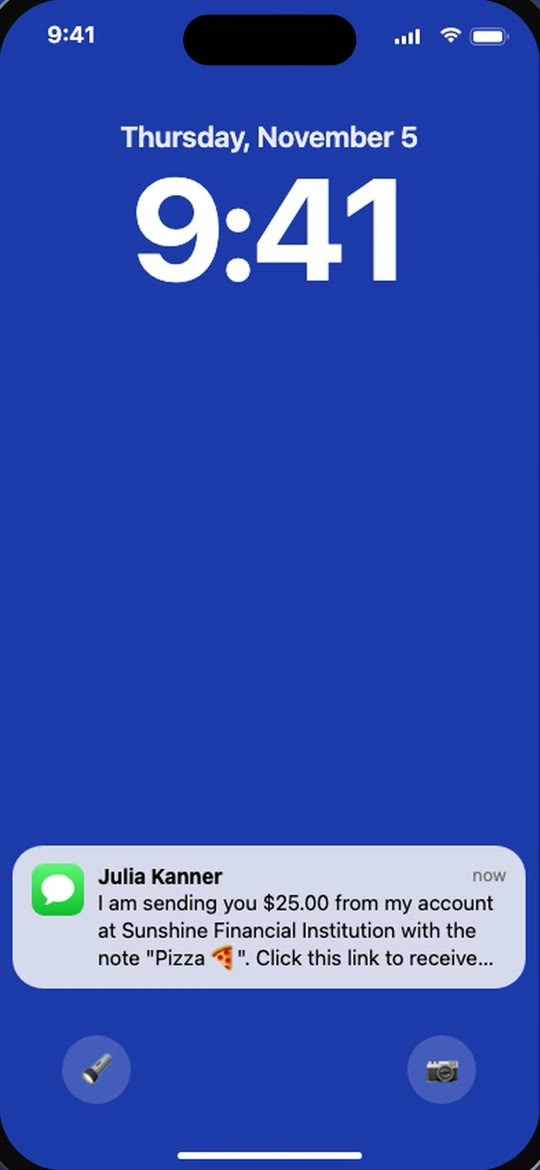
Recipient
Debit card, bank account or digital wallet. No download or sign-up required.
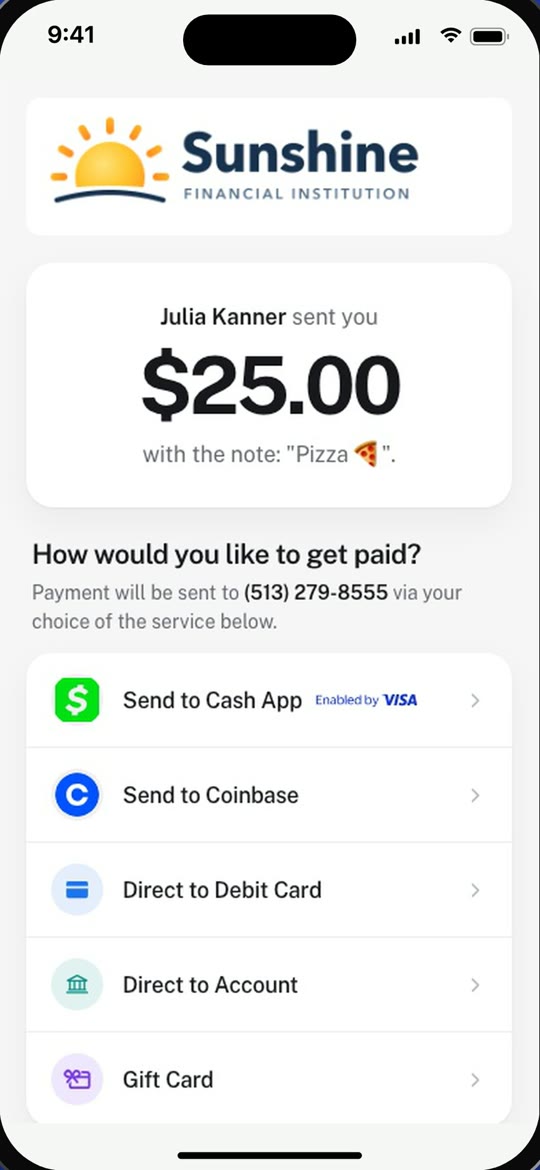
Recipient
Done in under a minute, start to finish, under your brand the whole time.
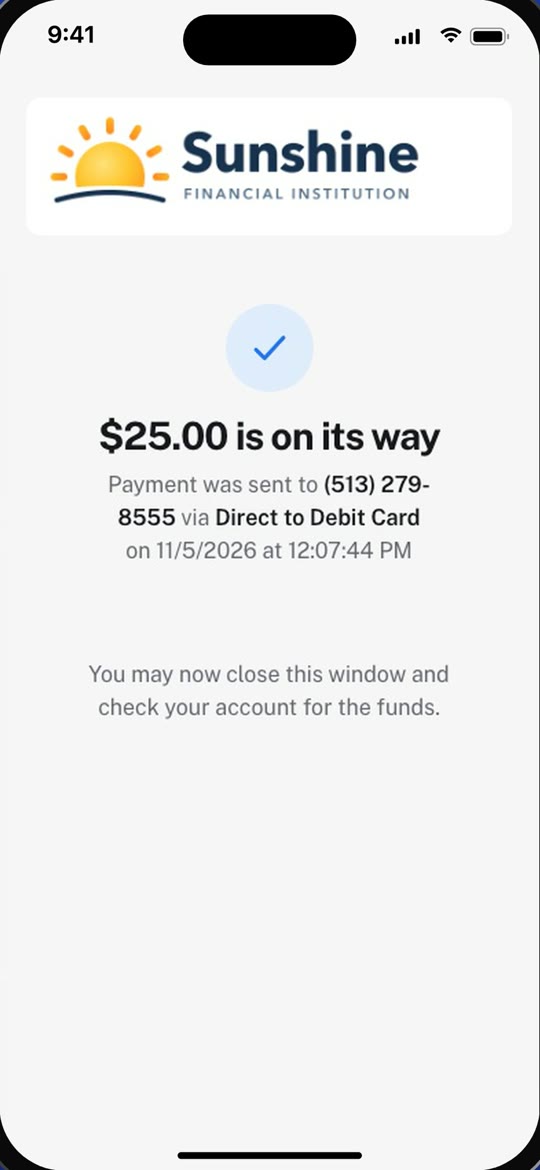
White Label
Your brand is the reason members trust you with their money, and we treat it that way. Neural Payments P2P is fully white-labeled, so the send flow, the text message and the claim page all look like you, not us.
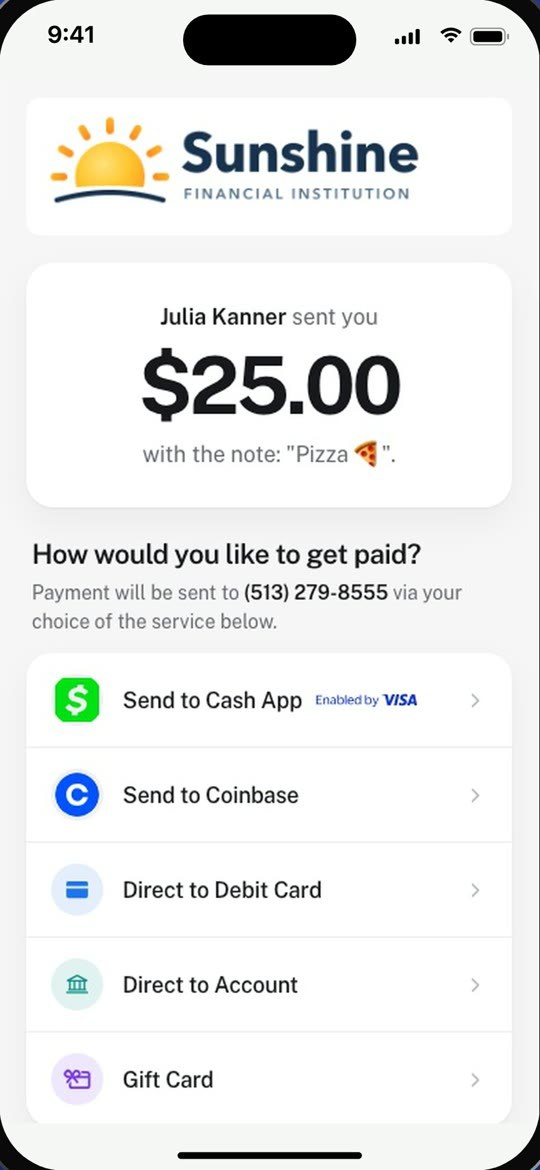
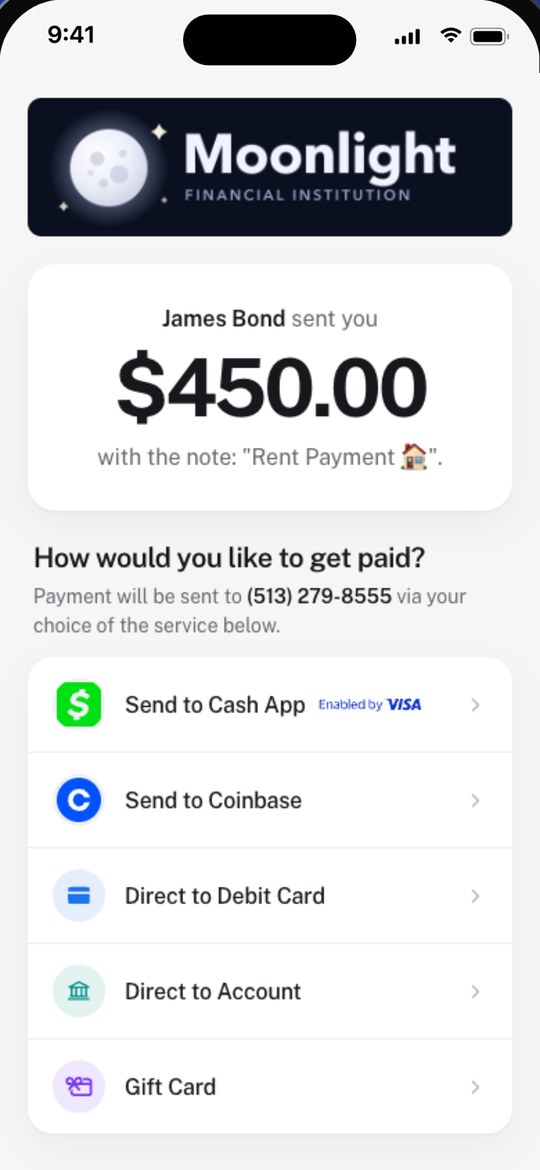
Request For Pay
Members request money by phone number or email from anyone, including people who do not bank with you. The person paying lands on a page with your name and logo on it, so every request is a small piece of word-of-mouth marketing your members do for you.
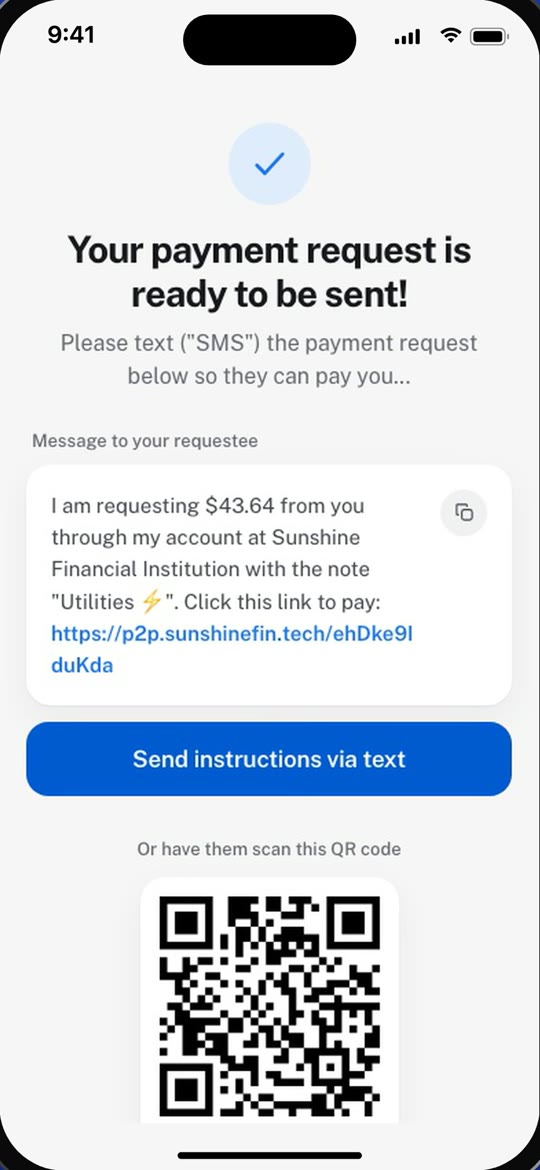
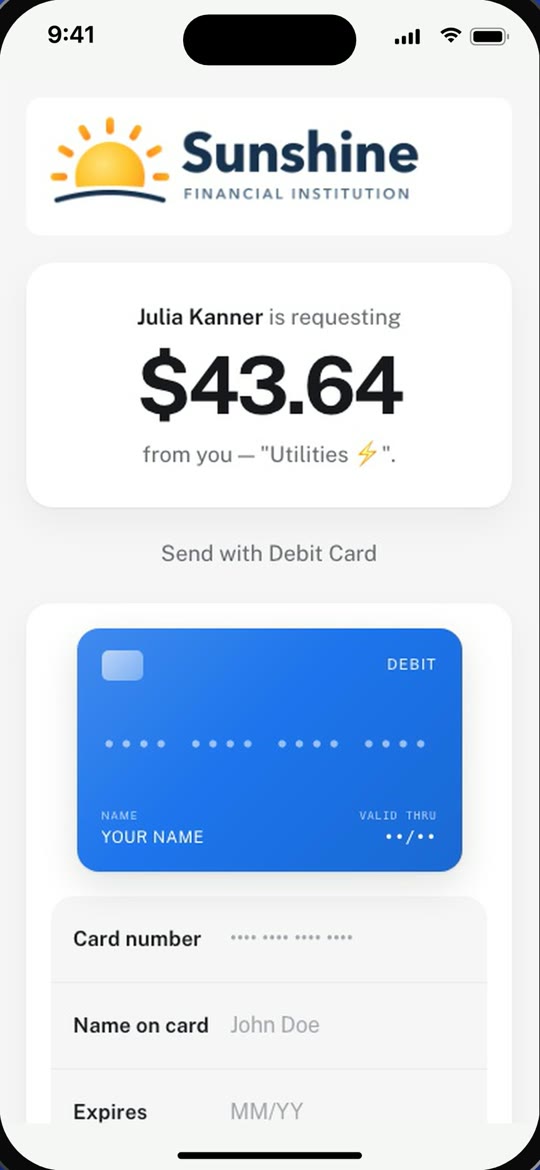
Out-of-network friends, roommates and customers pay from any debit card. They never need an account with you, an app or a login.
Every request puts your logo in front of someone new, with a personal referral from a member they already know. Organic reach, no ad spend.
Requested funds land with your institution instead of a third-party wallet, so requests grow deposits and engagement at the same time.
When the payer already uses your app, the request shows up there. They pay with a prefilled send or decline it.
The person being asked is checked against your exclusion lists before a link is ever sent, and open requests expire after 7 days.
Request For Pay is turned on per institution, so you choose when your members get it.
Scheduled And Recurring
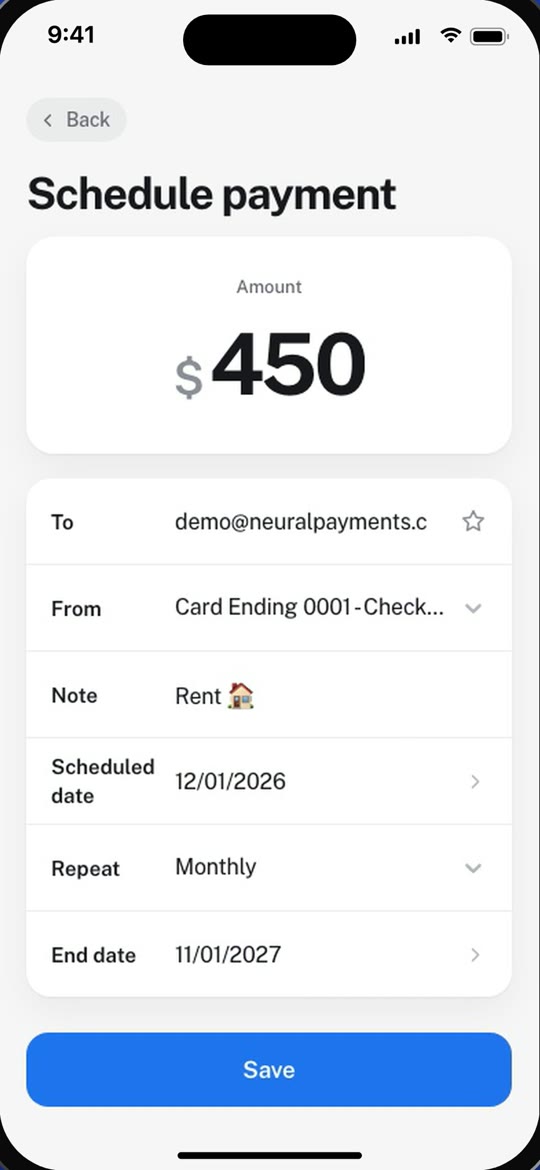
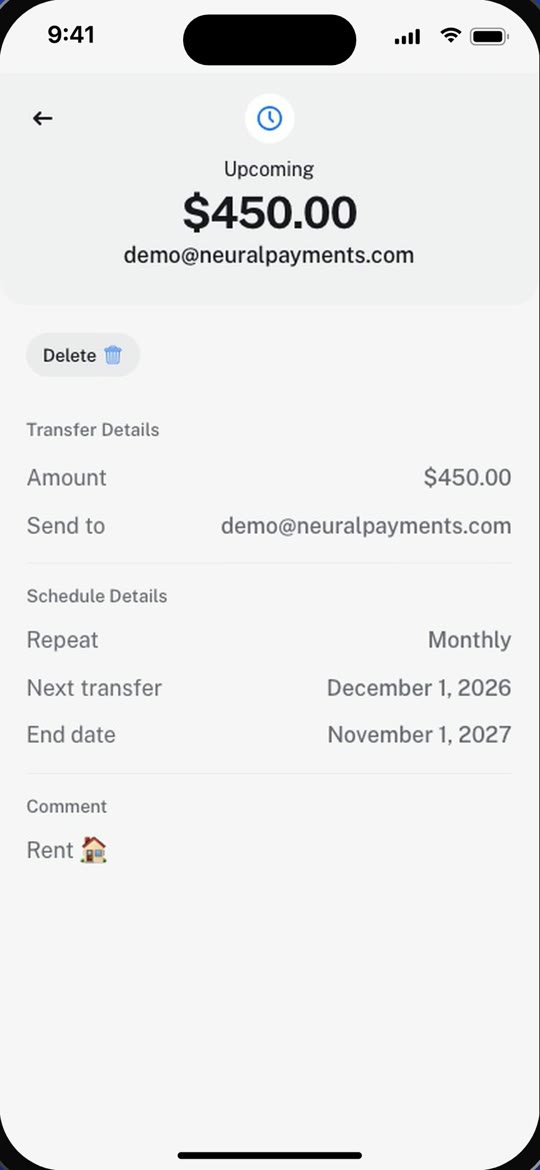
Members can schedule a payment for a later date or set it to repeat, so recurring payments like rent, allowance or a split utility bill go out on time without anyone having to remember.
Try It
Choose how the recipient receives it.
“The P2P payment landscape is evolving, and customers expect more than just speed. They demand simplicity, security, and reliability. Neural Payments empowers your institution to deliver on these expectations while maintaining full control over branding, customer relationships, and operational efficiency.”
FAQ
No. Recipients receive a text or email with a secure claim link and choose a bank account, debit card or digital wallet. No app download or sign-up is required.
No. Most of the institutions we work with already offer Zelle, and Neural Payments runs alongside it. It fills the gaps Zelle does not cover, such as push-to-card and payouts to recipients who choose a debit card or digital wallet, under your own brand.
Yes. Neural Payments P2P is fully white-labeled. The send flow, the text message, the claim link and the claim page all carry your institution’s logo, colors and name, so recipients who do not bank with you still meet your brand.
Yes. Members can schedule a payment for a later date or set it to repeat daily, weekly, every two weeks, twice a month or monthly, with an optional end date. They can see the next payment and past payments, and cancel at any time. Scheduled payments go through the same fraud screening as any other transfer.
Request For Pay lets members ask anyone for money by phone number or email. If the person already uses the institution’s app, the request appears there. If not, they get a link and pay from any debit card on a page branded for the institution, with no app or account needed. The person being asked is screened against exclusion lists before a link is sent, and open requests expire after 7 days.
Most institutions go live in as little as 90 days, using pre-built integrations with leading digital banking providers.
Neural Payments helps banks and credit unions futureproof their payments strategy. Its AI-powered payments hub powers FI Payouts for the institution itself, P2P, account funding and FedNow access inside the institution’s existing digital banking app, without rebuilding the stack.
AI is part of how every payment moves. Each payment gets a Neural Payments AI Risk Score from 1 to 10 before it is sent, based on the sender’s history and fraud signals such as new devices, recent credential changes, unusual amounts and recipient risk. The institution’s rules decide what happens next: approve, hold, reject, suspend the user or ask for step-up authentication.
No. Most of the institutions we work with already offer Zelle, and Neural Payments sits alongside it. We fill the gaps Zelle does not cover, such as business payouts, push-to-card and small-business payments.
For your institution: instant disbursements and payouts across FedNow, RTP, ACH and push-to-card.
Real-time, configurable fraud controls included with every product.
Turn on FedNow through the Neural Payments Hub in as little as 30 days.
Members load new or existing accounts from an outside debit card in seconds.